UNIFINplatform

Solution

Unifin Swaps

The suite runs a swap from a quote to a repository report under limit control.
Quote requests to dealers, pre-trade checks, same-day confirmation, collateral and quarterly compression.
The portfolio is valued, coverage is in place and the regulatory view matches the books.

  • The OTC suite
  • Quote requests
  • Repository reporting
All solutions

Live screens from the product terminals

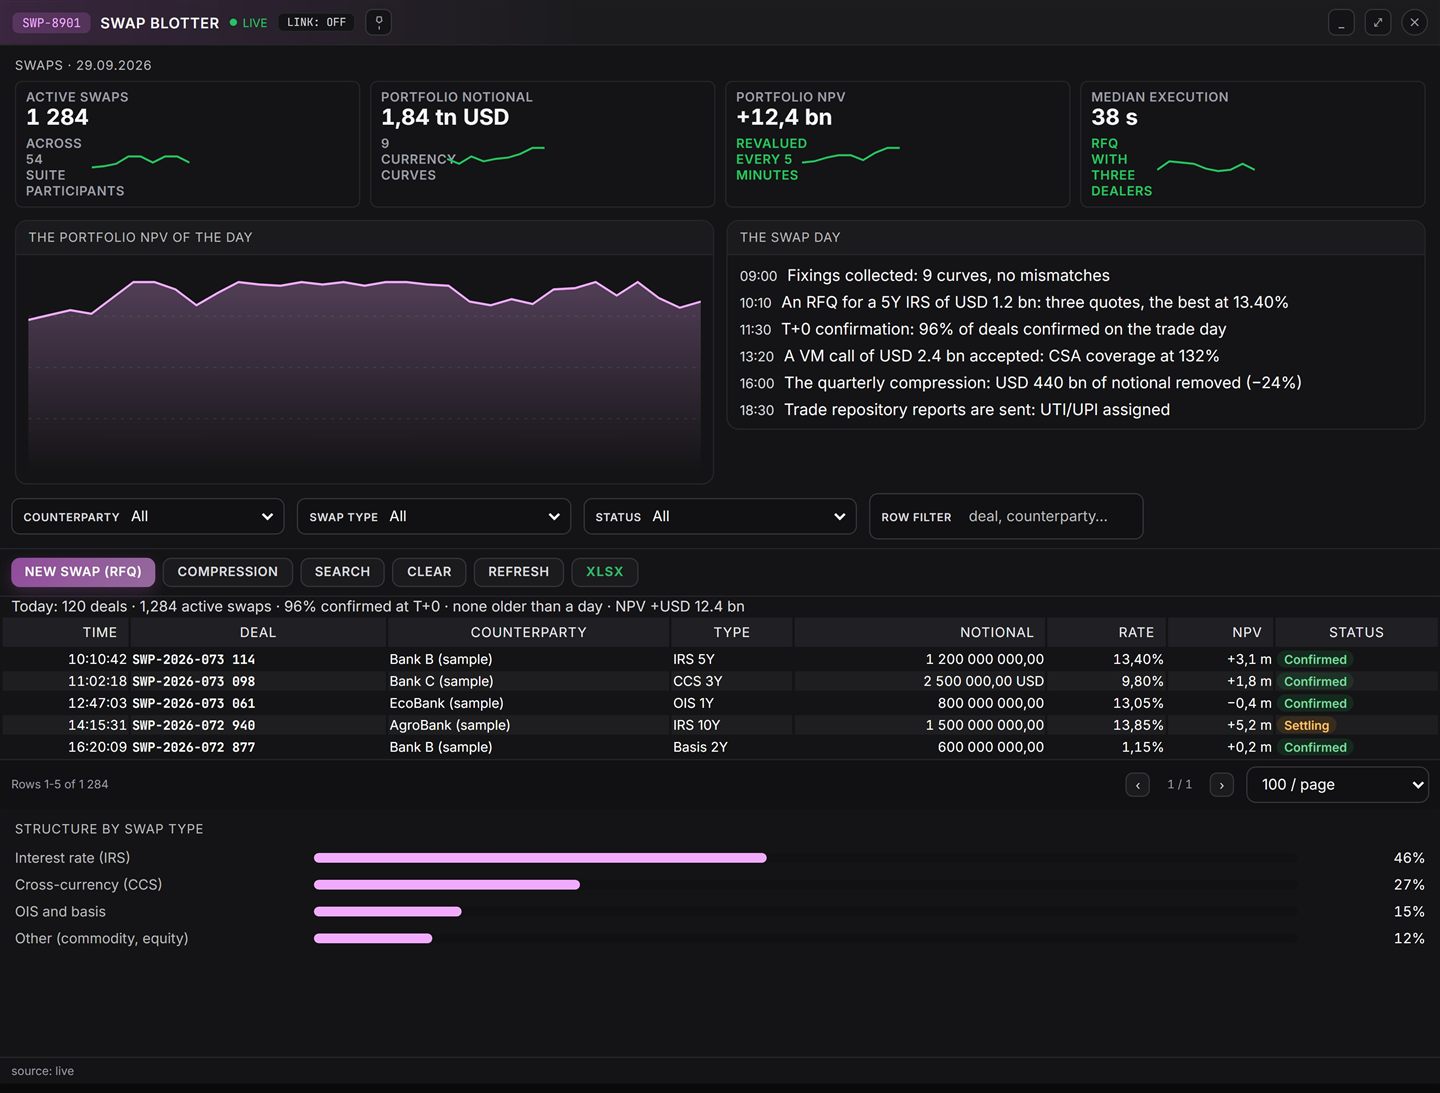
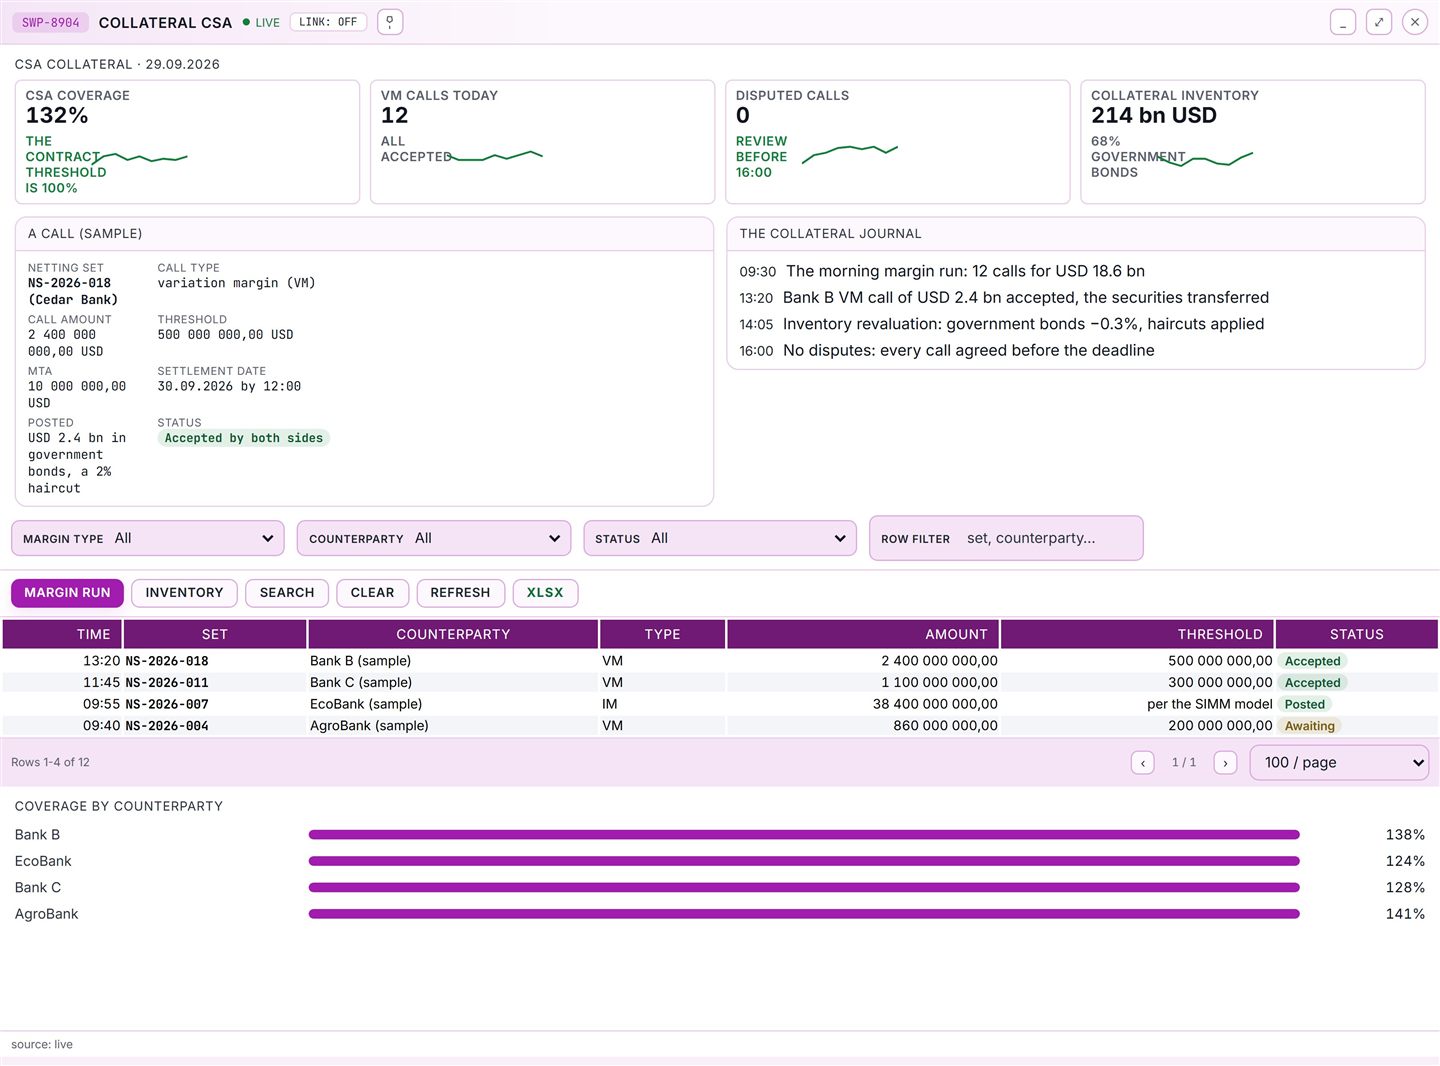
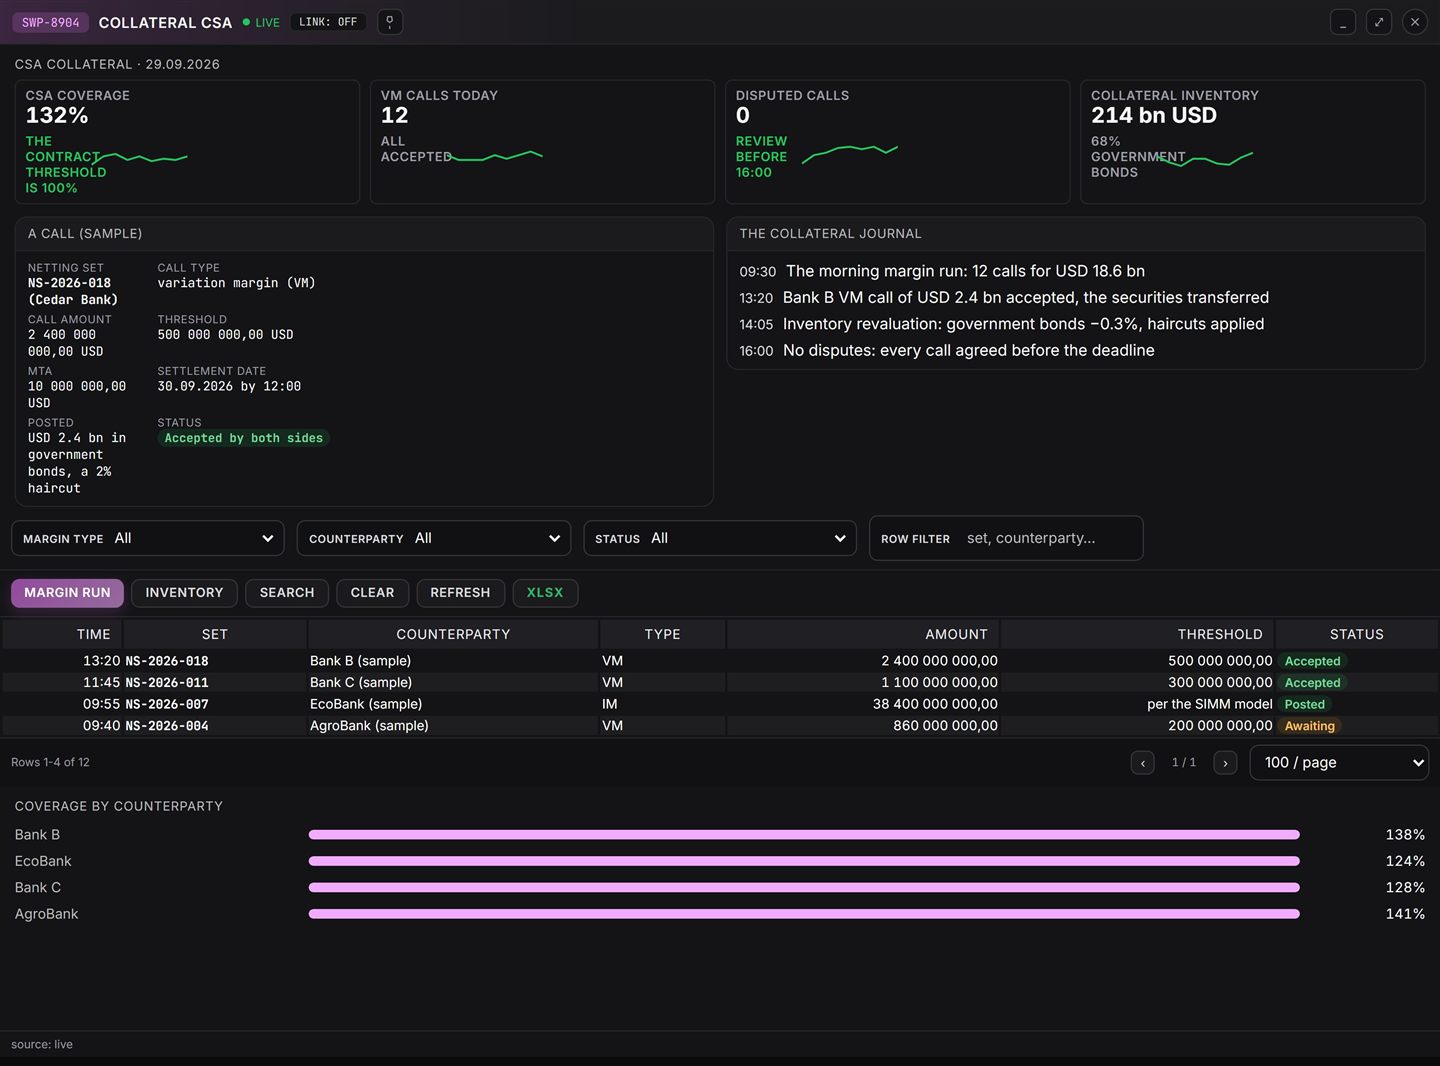
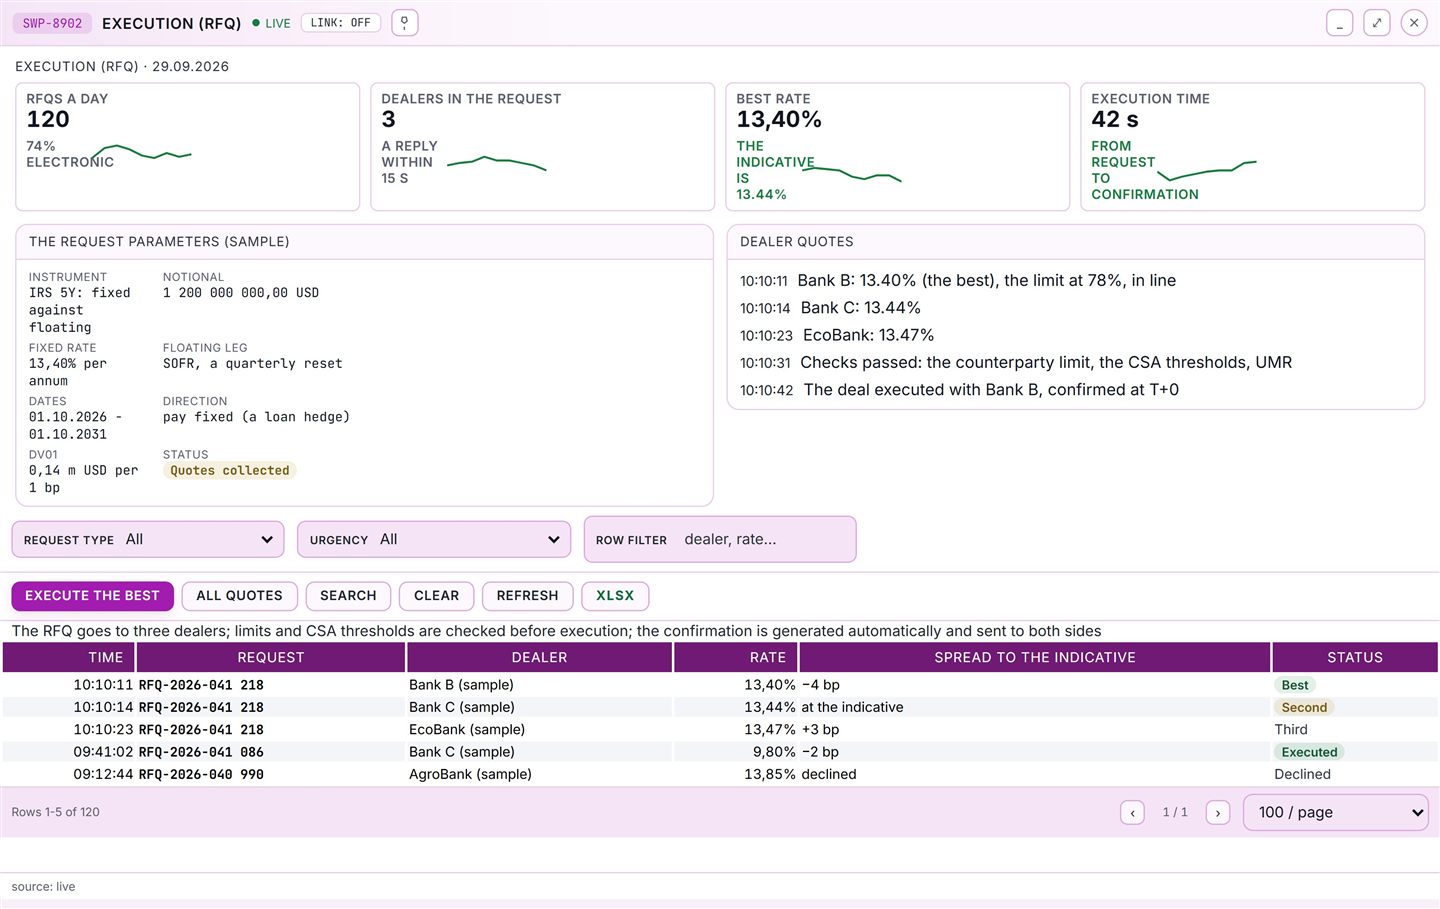
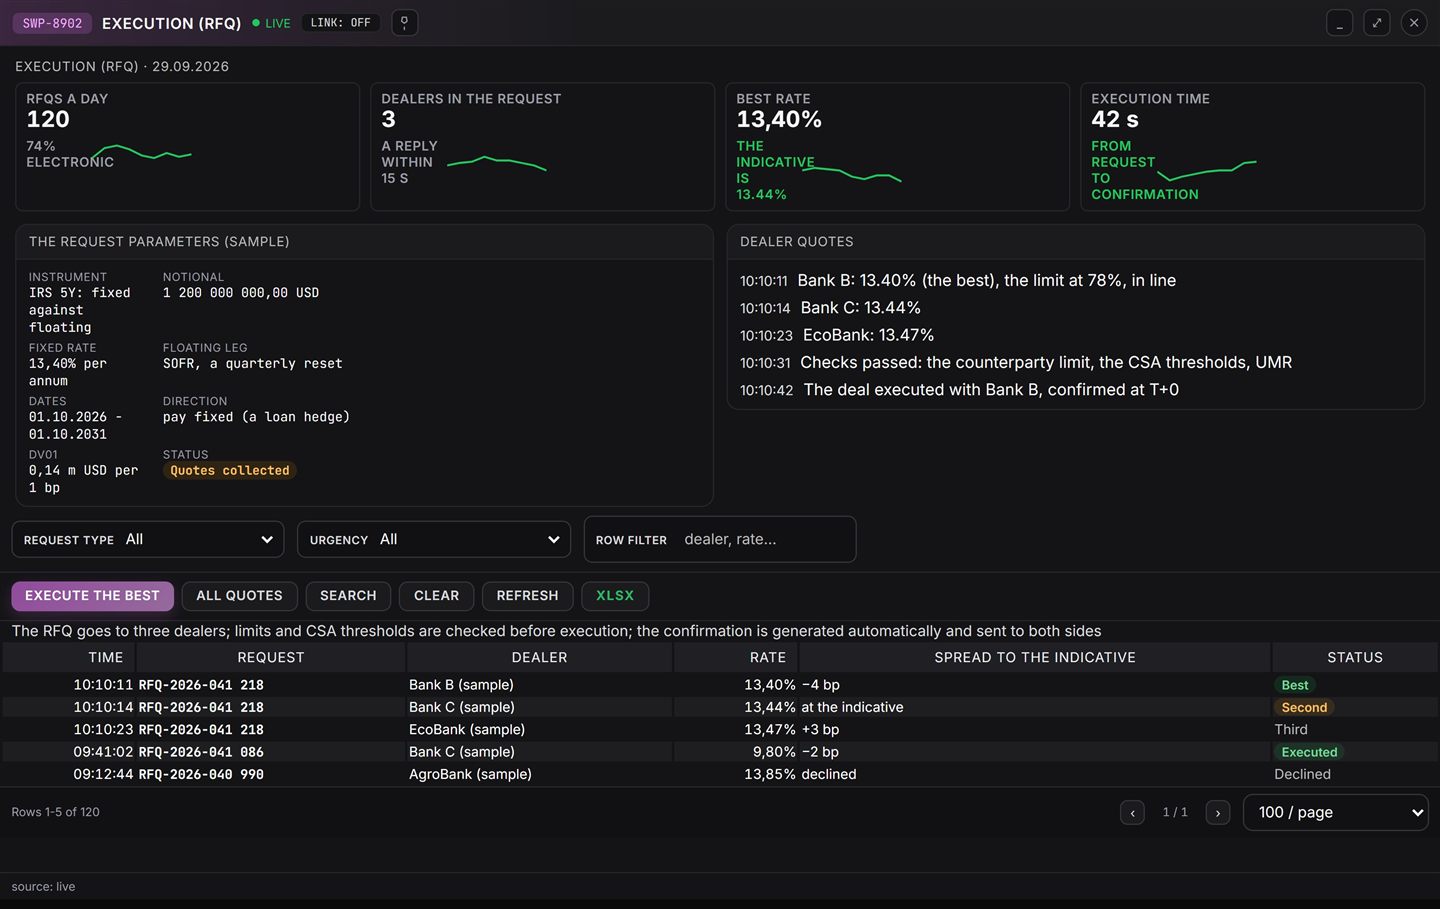
Swap blotter screen with active swaps Swap blotter screen with active swaps Collateral CSA screen with margin calls Collateral CSA screen with margin calls RFQ execution screen with dealer quotes
Demo Unifin Swaps Theme Open separately
Swap blotter
Swap blotter

This is an interface demonstration: the real solution will differ in colours and content for a specific project.

Functions at a glance

Business functions at a glance

From quote requests to repository reports.

Quote requests
Requests dealer quotes, executes the best after checks
A competitive rate and pre-checked limits
Same-day confirmation
Reconciles terms against the standard templates, assigns a trade ID
A confirmed deal on the trade day
Event lifecycle
Runs fixings, rate resets, payments and expiries by calendar
No payment or fixing is missed
Deal collateral
Calculates coverage and initial margin, watches thresholds
Coverage in place, no disputes
Portfolio valuation
Refreshes NPV and DV01 across the currency curves
Portfolio value visible at any moment
Netting and compression
Closes the quarter with one net, removes part of the notional
Fewer payments and less capital posted
Repository reports
Prepares reports with trade IDs, stores the receipts
The regulatory view matches the books

What runs today

The swap lifecycle, already running

Quote to compression: the live lifecycle.

Quote requests

Quote requests go to dealers in one flow.

Confirmation

Same-day confirmation closes the deal.

Collateral

Deal collateral runs in the circuit.

Valuation

Valuation and curves value the portfolio.

Compression

Quarterly compression reduces the book.

Roadmap

Clearing connectivity beyond the suite is next.

Solution description

Capabilities and overview

Key features

  • Execution by dealer quote requests
  • Limit and term checks before the trade executes
  • Same-day confirmation against standard templates
  • Lifecycle: fixings, resets, payments and expiries
  • Deal collateral: coverage and CSA initial margin
  • Portfolio valuation: NPV and DV01 across currency curves
  • Quarterly netting and notional compression
  • Trade repository reports with receipts
  • Trade identifiers at every stage
  • Payment calendar and participant notifications
  • Journal and audit for every swap event
  • Deployment: by configuration, within the UniFin platform

Product overview

Unifin Swaps is the UniFin platform OTC swap suite for banks, brokers and corporations with interest rate and currency risks.

The suite runs a swap from quote requests to the repository report: execution, confirmation, collateral, netting and compression.

The portfolio is revalued across curves, coverage stays in place, and the regulatory view matches the books.

Every step is confirmed with documents and identifiers, while the calendar holds the event deadlines.

The solution runs within the UniFin platform and is configured to the counterparty and limit policy.

What it delivers

What the solution delivers

Quote requests

Dealer quotes are usually collected over the phone: rates arrive one by one and the trade history gets lost in a mailbox. The solution sends the request in one action. Gathers the quotes on one screen and executes the best one after limit and collateral checks. With the solution the rate is competitive and execution stays inside the limits. Dealing hours go into the trade, not into calling around. In setup the dealer list, the channel (portal or FIX) and the checks come as reference data without code changes. Every quote and decision stays in the journal.

Same-day confirmation

A term mismatch usually surfaces the next day, when the trade is booked and arguing is expensive. The solution reconciles the terms against the standard templates within the day and assigns the trade ID right away. With the solution there are no settlement pauses or penalties over disputed confirmations, and reconciliation takes fewer manual hours. In setup the event queue (fixings, rate resets, payments, expiries) and the version history are visible. Any change can be pulled up with its author and time.

Event lifecycle

Fixings, rate resets and payments usually live in calendars owned by different people, and one missed date surfaces at the worst moment. The solution runs the contract events by calendar and warns in advance. A fixing is checked against the source, the rate resets and a payment lands on the settlement date. With the solution there are no late fees, and no one keeps dates under manual control. In setup the event queue is visible with statuses and reminders. The calendars and calculation rules are set in configuration without code changes.

Deal collateral

Collateral requirements are usually calculated late in the evening, and until then coverage is unclear. The solution calculates coverage and initial margin during the day and shows what is missing before the counterparty call. With the solution the collateral is exactly what the agreement requires, with no buffer until settlement, and fewer late fees. In setup thresholds and minimum transfer amounts are configured per segment, eligible assets are visible in one list. Every requirement carries a due date and an owner.

Portfolio valuation

When the portfolio is priced once a week, decisions ride on a picture from yesterday. The solution refreshes NPV and DV01 across the currency curves. Front office and risk control read one set of figures. With the solution the risk is visible in the moment, no extra capital is held for a past scenario. The desks argue about trades, not numbers. In setup the recalculation schedule and the source reconciliations are managed, and the views by counterparty and set come from one model.

Netting and compression

The quarter is usually closed with a manual net: notional is matched in spreadsheets. Every notional left on the books pulls collateral and capital with it. The solution closes the quarter with one net and removes part of the notional on the selected trades. With the solution fees are lower, and less capital stays tied in collateral. In setup the trade selection and the NPV and DV01 recalculation are visible before and after. The cycles and selection rules come from the setup.

Repository reports

Repository reports are usually assembled by hand from different tables, and every inaccuracy turns into correspondence with the regulator. The solution prepares the reports on schedule from the same picture as the books and stores the acceptance receipts. With the solution requests are answered without rush periods, and there are no late-reporting fees. In setup the report scope, the sending queue and the receipts are visible for every trade. The formats and selection rules are part of the configuration.

Coverage

What it covers

One route: quote, deal, confirmation, compression.

Quote request

Requests over the portal and FIX, quotes and pre-trade checks in one pass.

Confirmation and lifecycle

Standard templates, a calendar of fixings, rate resets and payments.

Deal collateral

Margin calls with thresholds and a timed dispute workflow.

Valuation and curves

Currency curves with an NPV and DV01 refresh and source reconciliations.

Netting and compression

Netting sets, quarterly tri-party cycles validated by NPV and DV01.

Settlement

Both legs netted per set; the quarterly net reconciliation with the counterparty.

Trade repository reporting

Trade IDs, repository reports and receipts in the journal.

Journal and audit

Every quote, confirmation, call, substitution and report kept in the platform journal.

Stand

Screens of the solution

The swap blotter, the quote request and the new swap ticket, the yield curves desk and deal collateral.

Swap blotter screen with active swaps
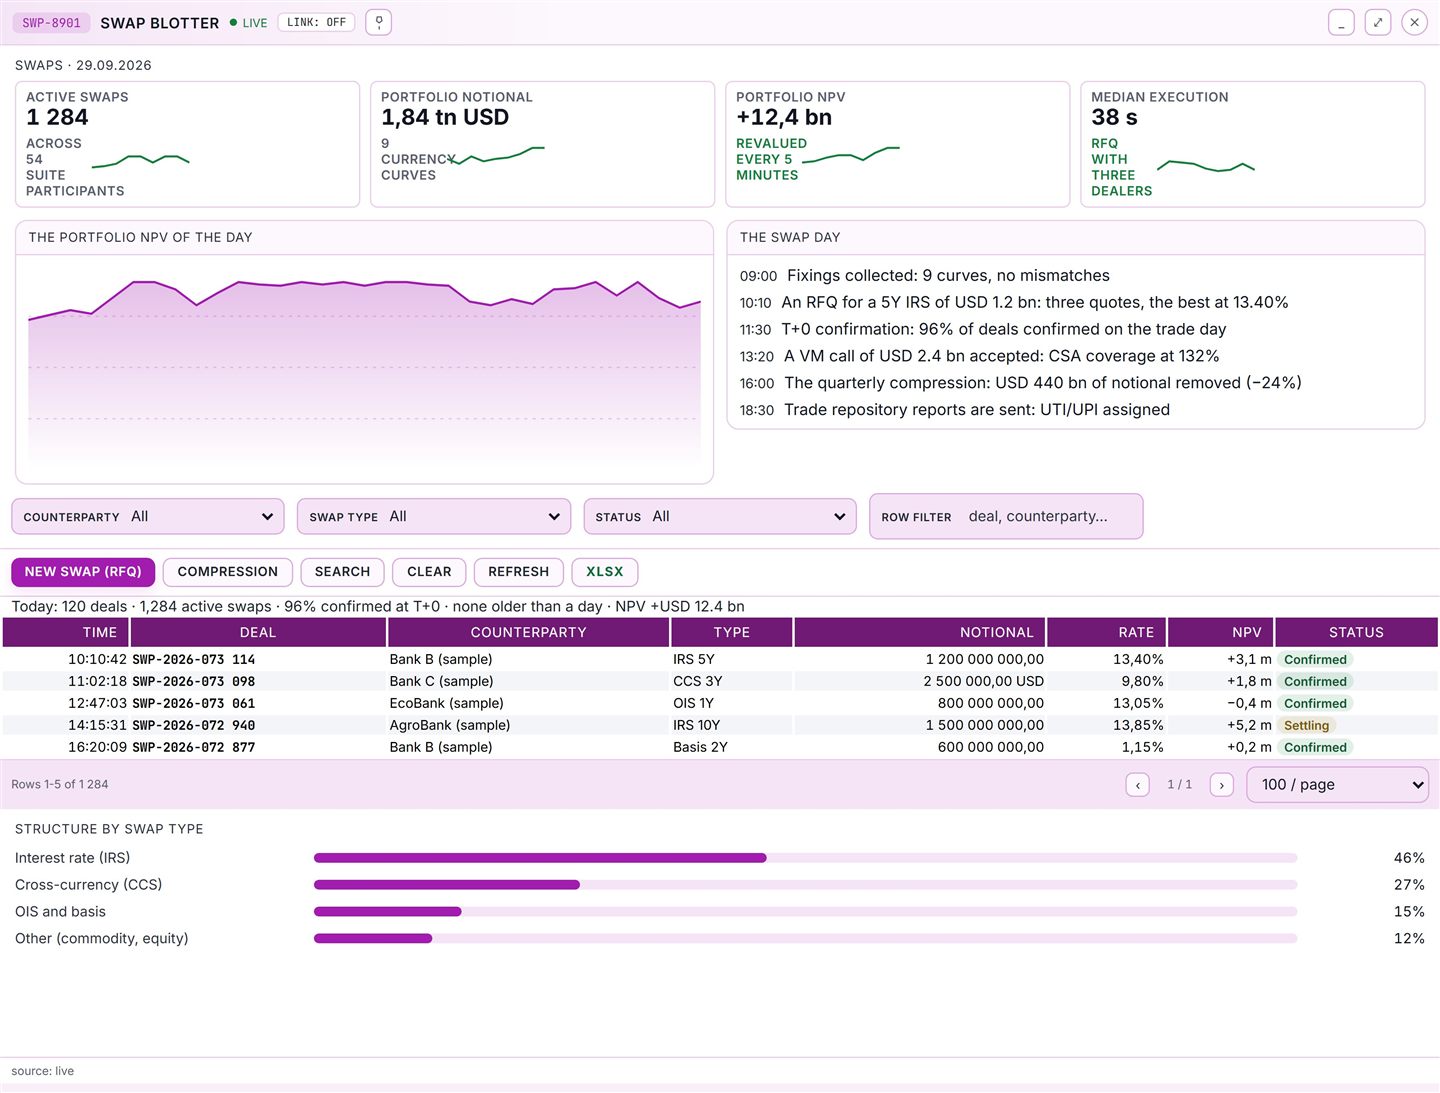
Swap blotter: active swaps, NPV, rates and the day journal
RFQ execution screen with dealer quotes
Execution (RFQ): the request, dealer quotes and the best rate
Collateral CSA screen with margin calls
Collateral CSA: calls, coverage and the inventory
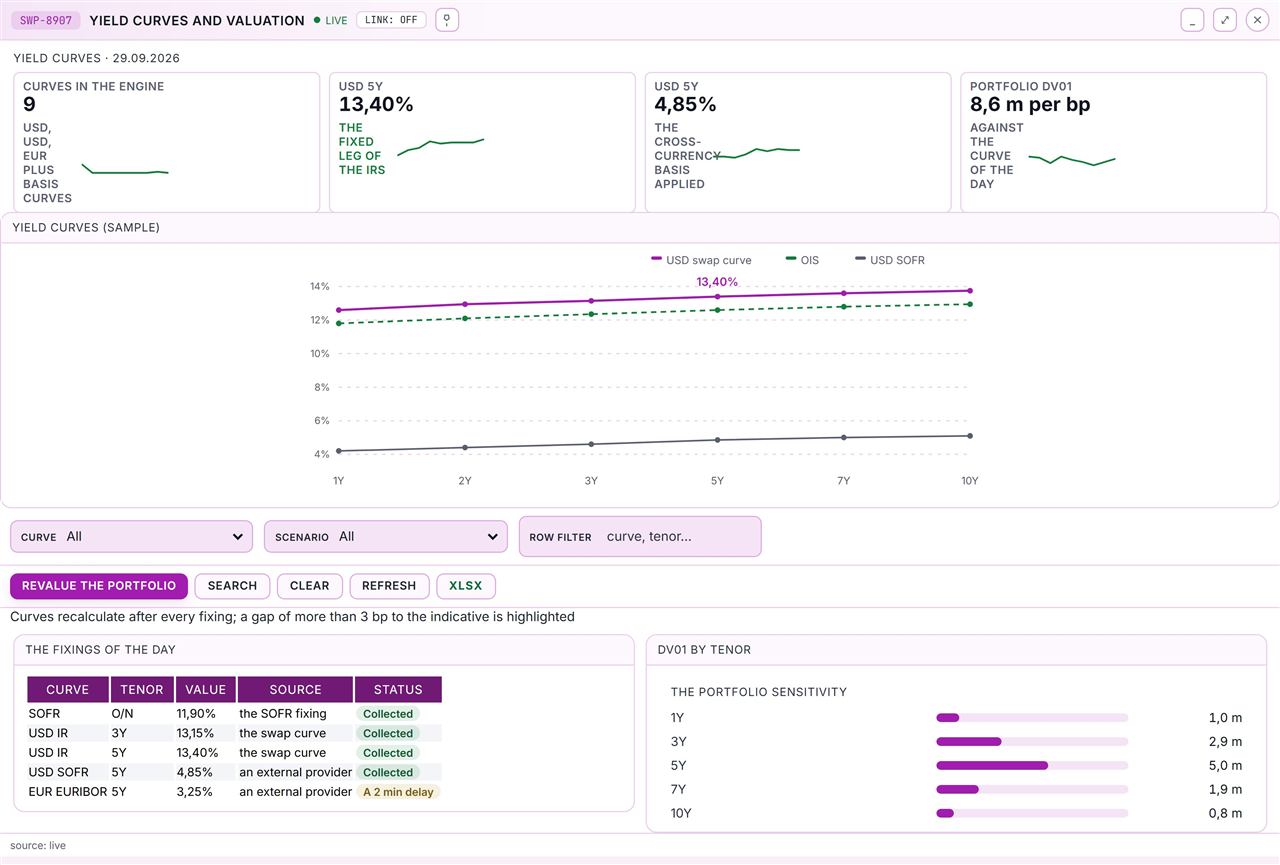
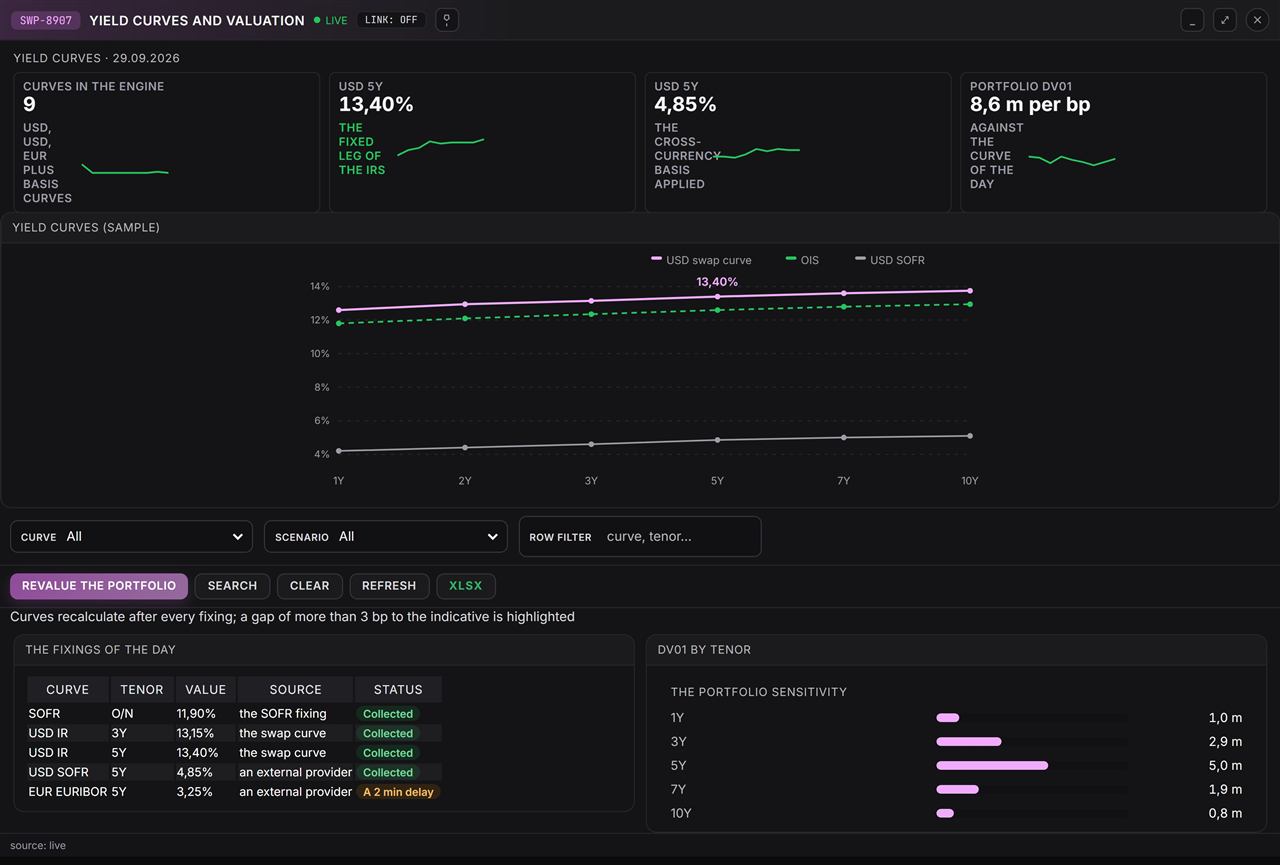
Yield curves screen with USD and EUR curves and fixings
Yield curves: USD and EUR curves, the day fixings and DV01 by tenor
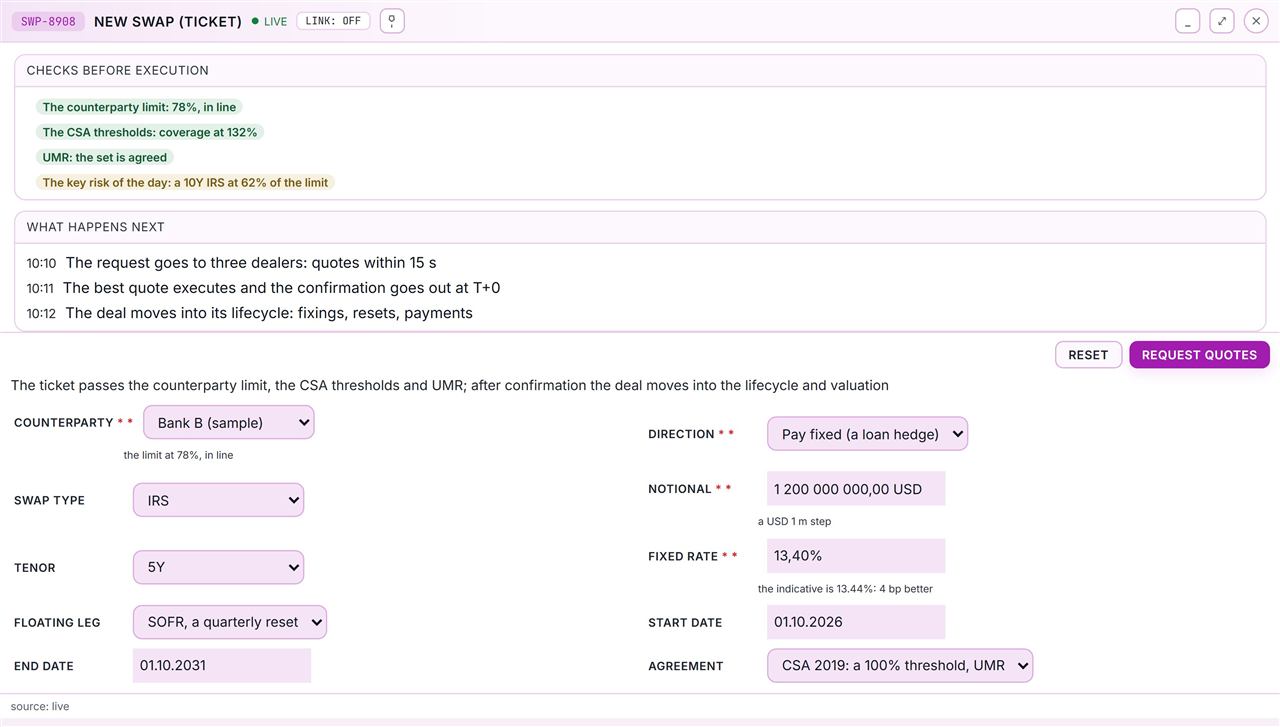
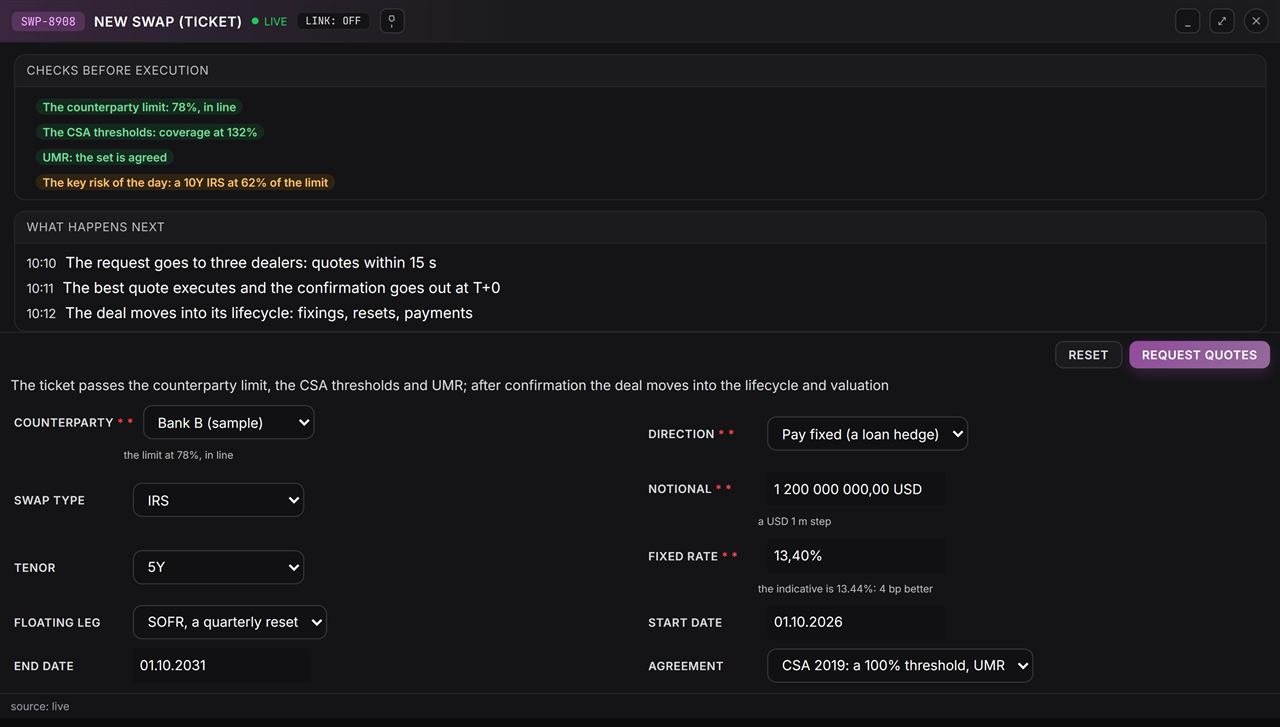
New swap ticket form with the pre-trade checks
New swap ticket: counterparty, notional, tenor, fixed rate and the pre-trade checks
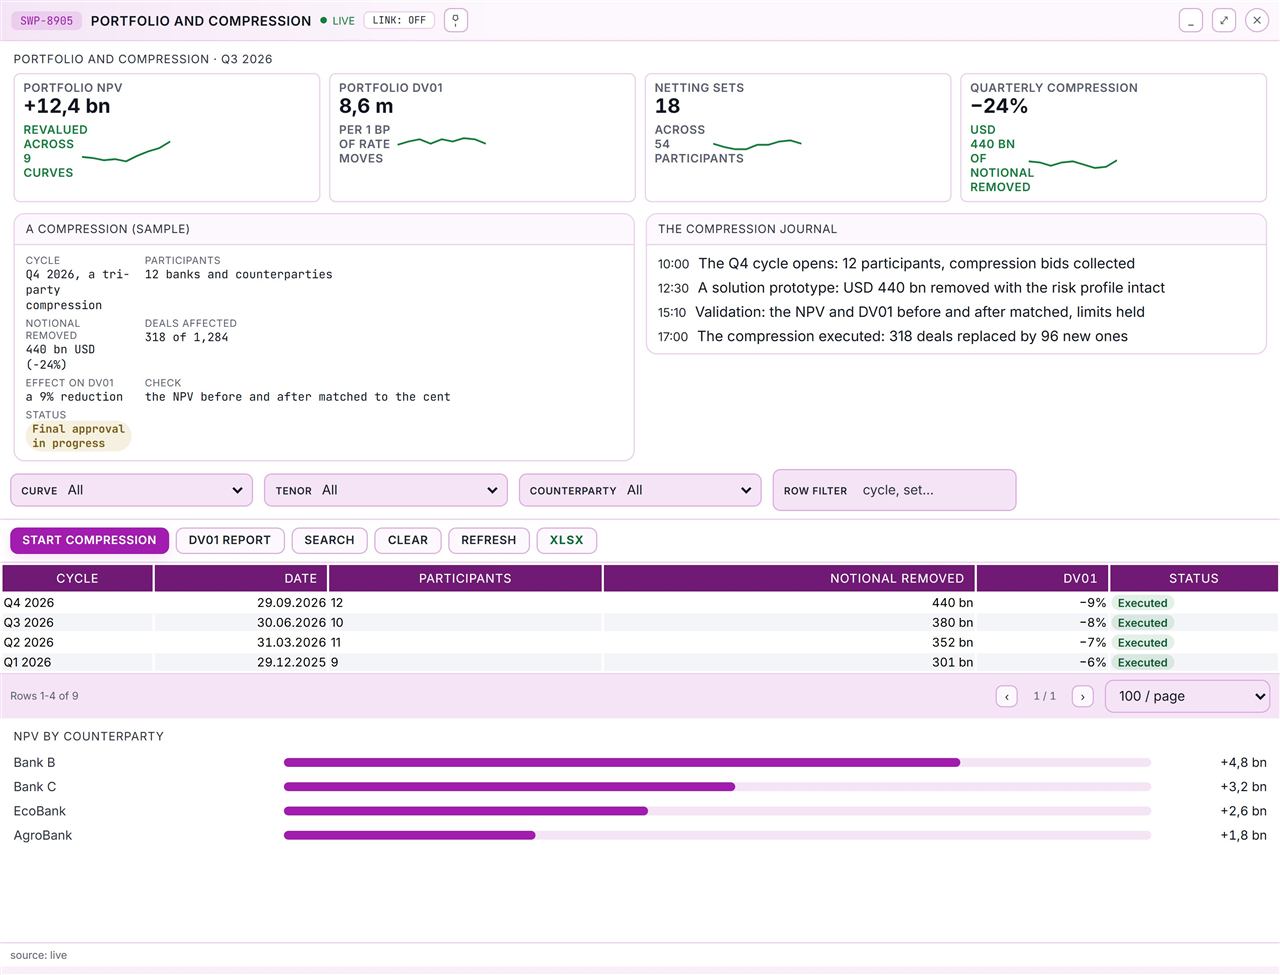
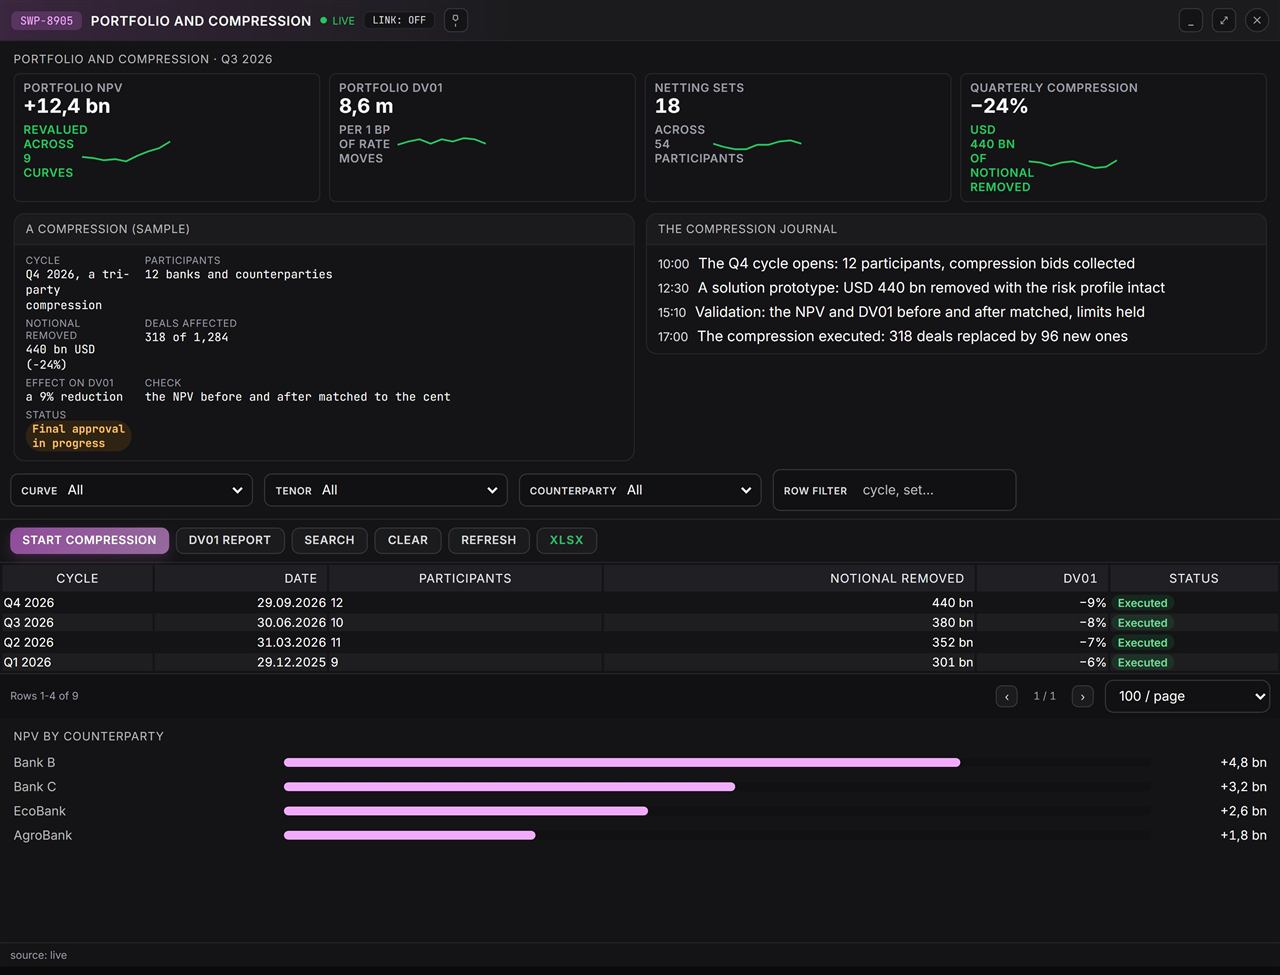
Portfolio and compression: NPV by counterparty, DV01 and cycles

How it works

From a quote request to settlement in five steps

One swap: a request, checks, a confirmation, events and the net.

  1. 1

    The quote request goes out

    A desk requests dealer quotes; the indicative rate shows.

  2. 2

    Checks before execution

    Limits and collateral thresholds pass in one pass.

  3. 3

    Execution and confirmation

    The best quote executes; the confirmation is signed.

  4. 4

    Lifecycle on the calendar

    Fixings reconcile, the rate resets and payments join the net.

  5. 5

    Settlement and reporting

    The quarter closes with one net and repository reports are accepted.

Industries

Industries it serves

The suite serves banks and brokers, corporates with interest rate and currency risks, asset managers and funds, and OTC infrastructure operators.

Exchange / venue

Trading, supervision, market data and post-trade on one governed core, launched by configuration.

Asset manager / fund

Analytics, indices and hedging instruments for portfolio and research teams.

Corporate / issuer

Market access for producers and issuers: auctions, deliveries, tokenised assets and data.

Fintech / data

Data products, AI services and API-first access to build on the platform.

Architecture

Architecture and access

The swap core: quote requests, confirmations, collateral, valuation, netting and reporting.

Service suite

The swap portal and six windows, BFF, quote requests, confirmations, collateral, valuation and netting.

External suites stay external

Dealers (FIX), the repository, the clearing house and accounting connect as connectors.

Multi-region and DR

Active-active read, a DR region for Tier-0, clusters Active-Passive/Active-Active and database replication.

Extend without touching the core

A new dealer, template or event joins through a connector: the core stays still.

AI layer

The AI layer sums up the day by counterparty and flags unusual quotes; people approve each call.

Architecture scheme The same architecture as a standalone page. Open the diagram separately

Readiness

Ready today, next in line

Next: portfolio reconciliation and margin optimisation; the base is in place.

Ready today

  • Quote requests to the market dealers
  • Same-day confirmation and the event queue
  • Deal collateral with coverage and a dispute-free margin run
  • Quarterly notional compression and repository reporting

Next in line

  • Portfolio reconciliation as a service for the buy side
  • Cross-set margin optimisation
  • Additional repository formats and clearing routes (roadmap)

Releases

Release history

Quarterly releases from the foundation of the platform (2020); the swap suite launched in 2026.

2026 Q1

  • Quote requests and same-day confirmations.

2026 Q2

  • Deal collateral and the quarterly compression cycle.

2026 Q3

  • Portfolio valuation and netting: curves, NPV and settlement sets.

2026 Q4

  • Portfolio reconciliation services and margin optimisation (plan).

Detailed description

Detailed description

The module map, the collateral terms and the delivery frame.

How the suite is assembled

Channels and clients
FIX 4.2 / 4.4 / 5.0, REST with mTLS, SFTP files, web portals
Edge and access
API gateway with 126 routes, Keycloak single sign-on, WAF and CSP
Platform core services
trading-ms risk-ms collateral-ms clearing-ms AI agentic layer Services of the suite on the shared platform core
Data and events
PostgreSQL 17 per service, Redis 7, RabbitMQ 3.13 quorum queues, transactional outbox
Results and reporting
Portals, reports, regulator and partner channels

Technology stack

Runtime and backend: Java 21 (LTS), Spring Boot 3.5.16, Spring Cloud 2025.0.3, Gradle, Flyway 10.15.

Data: PostgreSQL 17, Redis 7 with Sentinel, RabbitMQ 3.13 with the transactional outbox.

Market connectivity: FIX 4.4/5.0 for dealers, ISDA CDM exchange and signed file channels with the repository.

Portals: Next.js 16.3.3, React 19, TypeScript 5; Onest typography and two themes; Keycloak 26.1 for OIDC sign-in.

Delivery: Kubernetes and Helm, Vault secrets, Prometheus and Grafana, Docker Compose for pilots.

Evidence by default: quotes, confirmations, calls, substitutions and reports are journaled for five years.
Execution (RFQ)

  • A request goes to three dealers at once; quotes arrive within 15 seconds and the median route from request to confirmation is 38 seconds.
  • Counterparty and tenor limits, CSA thresholds and UMR pass before a deal executes; a deviation takes an explicit approval.
  • The best quote executes with its rate and source recorded: 13.40% against a 13.44% indicative in the sample.
  • Requests run over the portal and FIX channels; 74% of them are electronic.

Confirmations and lifecycle

  • Confirmations build from ISDA and DF templates; term reconciliation checks notional, rate, dates and calendars.
  • T+0 affirmation covers 96% of deals; nothing stays unconfirmed past the trade day.
  • Nine event types live in one queue: fixings, resets, payments, expiries and close-outs.
  • A fixing divergence blocks the reset until resolved; the case in the sample closed in 12 minutes.

CSA collateral

  • The 09:30 margin run values 18 netting sets and issues 12 calls for USD 18.6 bn in the sample day.
  • Coverage holds at 132% against the 100% contract threshold; thresholds, MTA and haircuts follow the CSA.
  • The USD 214 bn inventory (68% government bonds) is visible with substitutable positions.
  • Disputes: zero in the sample week; every call keeps its schedule, approver and journal record.

Portfolio and compression

  • USD 1.84 tn of notional revalues across 9 curves every 5 minutes; the day closes at +USD 12.4 bn of NPV.
  • Portfolio DV01 is USD 8.6 m per bp; sensitivity is visible by counterparty and tenor.
  • The quarterly cycle removed USD 440 bn of notional (−24%) by replacing 318 deals with 96 while the NPV stayed unchanged.
  • DV01 fell 9% after the compression; the validation report is stored with the cycle.

Architecture

  • Built from the platform core: trading-ms, risk-ms, collateral-ms and the clearing suite behind a portal BFF.
  • The portal BFF keeps roles, routing and audit; a window knows only its own /api/v1 calls.
  • Dealers (FIX), the trade repository, the CCP and the accounting system connect as connectors and reconciliations.
  • Scaling adds nodes: Patroni, RabbitMQ quorum queues and Redis clusters; stateless services run in three zones.
Detailed description

Leave your contacts to open the detailed description and download the PDF with architecture, cases and delivery details.

Ask about the swap suite

Bring one dealing day. We will show the path from a quote request to a confirmation and from a margin call to a compression cycle.